Financial Planning

5 tips for talking with your kids about money

To transfer generational wealth, start with the basics—financial literacy and open communication.
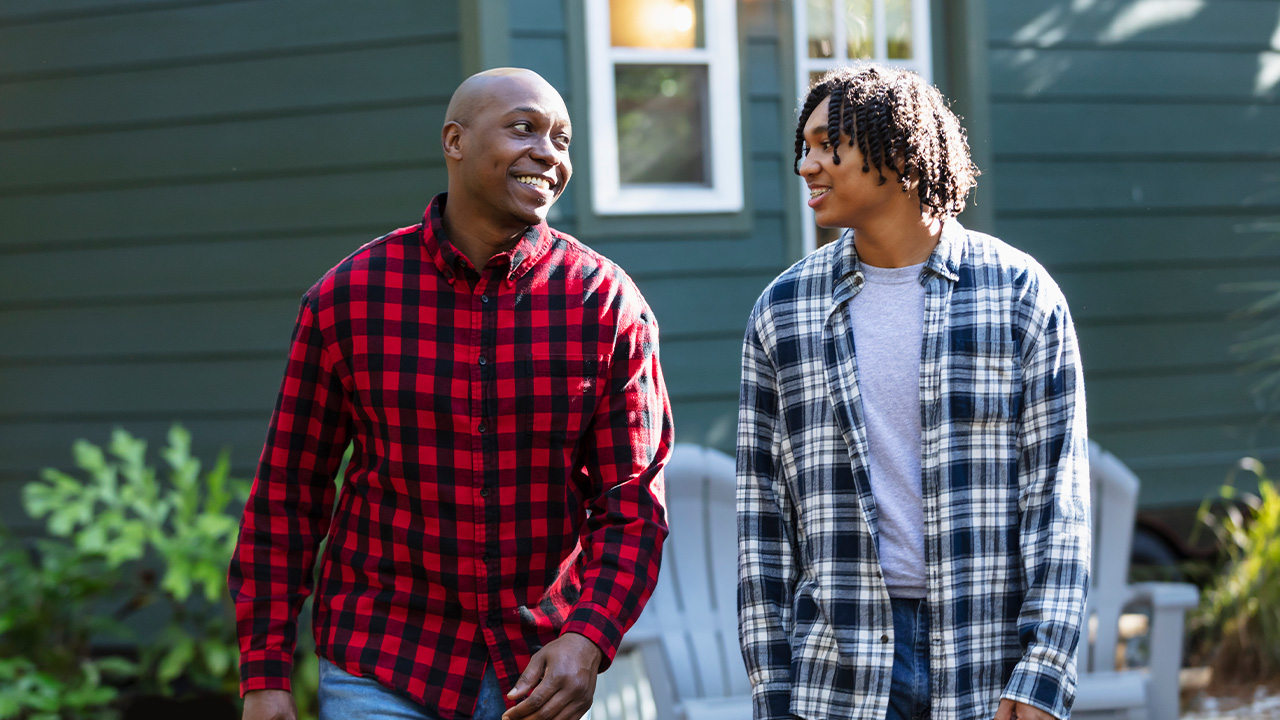
Years of research and conversations with families by the Truist Center for Family Legacy reveal a clear theme: Planning and resources alone can’t sustain generational wealth. Families achieve lasting success when heirs receive financial education, and when the family builds a habit of clear, open communication.

In a 2025 research report, the center found that the relational aspects of family wealth—practices like honoring family history and values, communicating between generations, and preparing heirs to be responsible stewards of wealth—are even more important than the financial aspects when it comes to sustaining that wealth across generations.

Financial education is a key part of preparing heirs, but the center’s research shows not enough families are doing it. While 96% of family members rated financial education as an important best practice, only 29% said they’re actually engaged in such discussions.

Why? David Herritt, senior managing director of the Truist Center for Family Legacy, says talking about wealth simply doesn’t come naturally.

“Parents are more willing to talk to their children about sex than about money,” says Herritt. “But if you’re not communicating about finances, how will you prepare them for their future responsibilities?”

Herritt adds that parents often fear that if their children know the details or extent of family wealth, they’ll become spoiled, unmotivated, or entitled. “They also worry their kids will feel isolated from friends,” Herritt says. “And as kids get older, parents may worry about what to say when estate plans change or conflicts arise.”

So how do you overcome some of these barriers? These five tips can help you open up about money with kids of any age.

1. Communicate your values early.

Herritt says you can begin discussions about money when your kids are as young as five years old. A focus on your family’s principles can be a good place to start.

“Your values and beliefs guide every decision in your life,” Herritt says. “If you communicate your values around money, then when you face a difficult decision or conversation, you can point back to those values.”

Herritt suggests creating a family mission statement that can help guide future financial decisions—and ensure everyone feels heard. “Family members can share what’s most important to them,” he says. “It helps create a roadmap based on what the family wants to accomplish in the future.”

2. Look for financial teaching moments.

Financial literacy is essential, but very few elementary, middle, or high schools include it in their learning plans. Parents can often find opportunities to teach kids about saving, spending, investing, and giving through everyday activities.

If you’re paying a bill or making a credit card purchase, for example, use the moment to educate your kids on financial topics like budgeting and maintaining a good credit record. You can also find age-appropriate books and apps to help reinforce the lessons. Look for topics that are important to your family, such as saving, investing, or philanthropy.

Parents are more willing to talk to their children about sex than about money.
—David Herritt, Senior Managing Director, Truist Center for Family Legacy

3. Emphasize family history.

Herritt also stresses the importance of teaching your children about your family history. When the next generation learns who built the family’s wealth and how they did it, they gain inspiration to protect the family’s legacy.

Make a habit of sharing family stories with your kids whenever you can. Storytelling can bring to life the challenges your family has overcome to get where it is today and help kids understand that the family’s bonds are deeper than money.

4. Give your kids some financial responsibility.

Including your children in financial decision-making processes can create additional learning opportunities for them. For example, let them participate in discussions about the budget for your next vacation and make choices about which activities fit.

“And let them make mistakes when the stakes are low,” says Herritt. “Kids who make mistakes will learn about consequences and will carry these lessons with them.”

For example, if you see your kids spending all their allowance money as soon as they get it, don’t step in with a loan when they want to spend more before their next “payday.” 

5. Don’t skip the hard talks.

Avoiding financial discussions altogether can unintentionally signal a lack of confidence in children’s ability to handle wealth responsibly.

“You want the next generation to have a seat at the table and know you’re willing to listen to them,” Herritt says. “Then, as they get older, they can step confidently into their role as responsible caretakers of the family wealth.”

Get support from the Center for Family Legacy.

If you’re looking to back up your conversations with additional educational opportunities, the Center for Family Legacy provides thought leadership resources on generational wealth, ranging from articles to podcast episodes.

Looking for financial planning advice for you and your family?

Talk to a Truist Wealth advisor today.

Truist Purple Paper. Managing personal wealth beyond the business. Strategies for business owners navigating growth, risk, and long-term security.
Truist Purple Paper©Managing personal wealth beyond the business

Strategies for business owners navigating growth, risk, and long-term security.

Related resources

Podcast: The executive’s planning challenge

Podcast: The executive’s planning challenge

Financial Planning Episode 46: The executive’s planning challenge

The complexities of executive compensation demand a thoughtful, flexible approach to wealth planning.

Podcast
09/08/2026
Podcast: The executive’s planning challenge

Truist Wealth specialists discuss the opportunities and complexities of executive compensation, managing concentration risk and liquidity, and the importance of financial goal-setting.

Podcast: When a loved one passes away—what families need to know

Podcast: When a loved one passes away—what families need to know

Estate PlanningEpisode 45: When a loved one passes away

It’s not easy to plan ahead for a death. But preparation can help ease the burden on those left behind.

Podcast
08/10/2026
Podcast: When a loved one passes away—what families need to know

Truist Wealth specialists discuss how advance planning for a death can help ease the burden on loved ones.

Podcast: Navigating life’s biggest transitions

Podcast: Navigating life’s biggest transitions

Business Owners Episode 44: Navigating life’s biggest transitions

Whether a change helps or hurts, it can be disruptive. Learn how to understand the impact and adapt.

Podcast
07/13/2026
Podcast: Navigating life’s biggest transitions

Hear a clinical psychologist discuss the challenges that even positive life changes can present, and advice for moving forward. | Truist Wealth

    {0}
    {6}
    {7}
    {8}
    {9}
    {12}
    {10}
    {11}

    {3}

    {1}
    {2}
    {7}
    {8}
    {9}
    {10}
    {11}
    {14}
    {12}
    {13}

    Stay informed and get connected

    Looking for fresh thinking and new opportunities? We’ve got you covered.

    Find an advisor

    Experience financial planning that goes beyond numbers.  By understanding your values and goals, we're equipped to help you navigate opportunities designed to help your wealth support the life you're building.

    Helpful links


    Like what you're seeing? Get it direct.

    Sign up for our Truist Perspectives emails to get tips and inspiration—right to your inbox.

    Please enter a first name
    Please enter a last name
    Please enter a valid email address