It’s a familiar financial reality for many medical professionals—providers being “wealthy on paper” yet constrained when cash is needed quickly. A $7 million net worth may include all illiquid holdings: $2 million in a primary residence, $1 million in vacation or investment real estate, $2 million in a 401(k) or IRA, $500,000 in life insurance cash value, and $1.5 million in practice equity.
When a family emergency or any other unexpected obligation arises, converting that wealth into accessible cash isn’t always straightforward. That’s why long-term, personal financial success for medical professionals requires a diversified balance sheet, including assets that can be converted to cash without penalties or significant tax exposure.
What practical tactics and broad strategies can help you simplify your access to cash? Here are four Ideas.
1. Examine your priorities.
After lagging income during your undergrad, med school, residency, and fellowship years, it’s only natural to want to catch up when you sign that first significant salary contract.
It can be hard to decide how to prioritize long‑term financial goals alongside day‑to‑day spending. Should reducing debt or boosting retirement savings take precedence? Working with a financial advisor can help you weigh the pros and cons of each alternative.
For younger physicians, a big part of putting together a plan is sorting through competing financial goals. Consider asking these questions:
- Is getting a bigger home, vacation property, or new car an urgent need?
- If I delay a purchase to pay down debt or increase retirement contributions, would that be more beneficial long-term?
For established medical professionals, keep asking those questions periodically with your wealth advisor to ensure you’re still striking a balance between wants and needs as your career, family, and lifestyle evolve.
2. Stay up to date on strategies that help you avoid asset liquidation.
Many physicians have a majority of their wealth tied up in assets that aren’t easily converted to cash, such as real estate and investments. That makes building a generously sized emergency fund a key part of your financial health.
But if your emergency fund gets tapped out, determining where to go for additional cash can be difficult.
“Because emergency funds can’t cover every unexpected need, we regularly work with established physicians to explore ways to extract liquidity from a variety of assets,” explains Neil Horowitz, wealth advisor with Truist Wealth Medical Specialty Group. “Any liquidity solution you consider needs to fit your particular circumstances, but categorically speaking, a second option we urge physicians to consider is borrowing.”
What could this look like? Through proactive planning and regular calibration, medical professionals can arrive at an asset mix that enables short-term borrowing strategies that generate infusions of cash at reasonable borrowing costs—all while avoiding the sale of any assets. Some possible short-term leverage solutions your Truist wealth advisor can help you with may include.
- Providing portfolio-secured lines of credit.Disclosure 1
- Extending margin loans.Disclosure 2
- Offering equity lines of credit on real estate holdings
- Recapitalizing owner-occupied real estate holdings
- Formulating and implementing creative practice buy-in structures
- Leveraging the cash value of life insurance policies
In certain situations, it may even make sense (based on your cash flow needs and situation) to recapitalize personal real estate holdings to generate additional liquidity.
3. Consider the benefits of illiquid assets.
Illiquid assets aren’t to be avoided. In fact, some illiquid assets can fill beneficial roles in your financial plan.
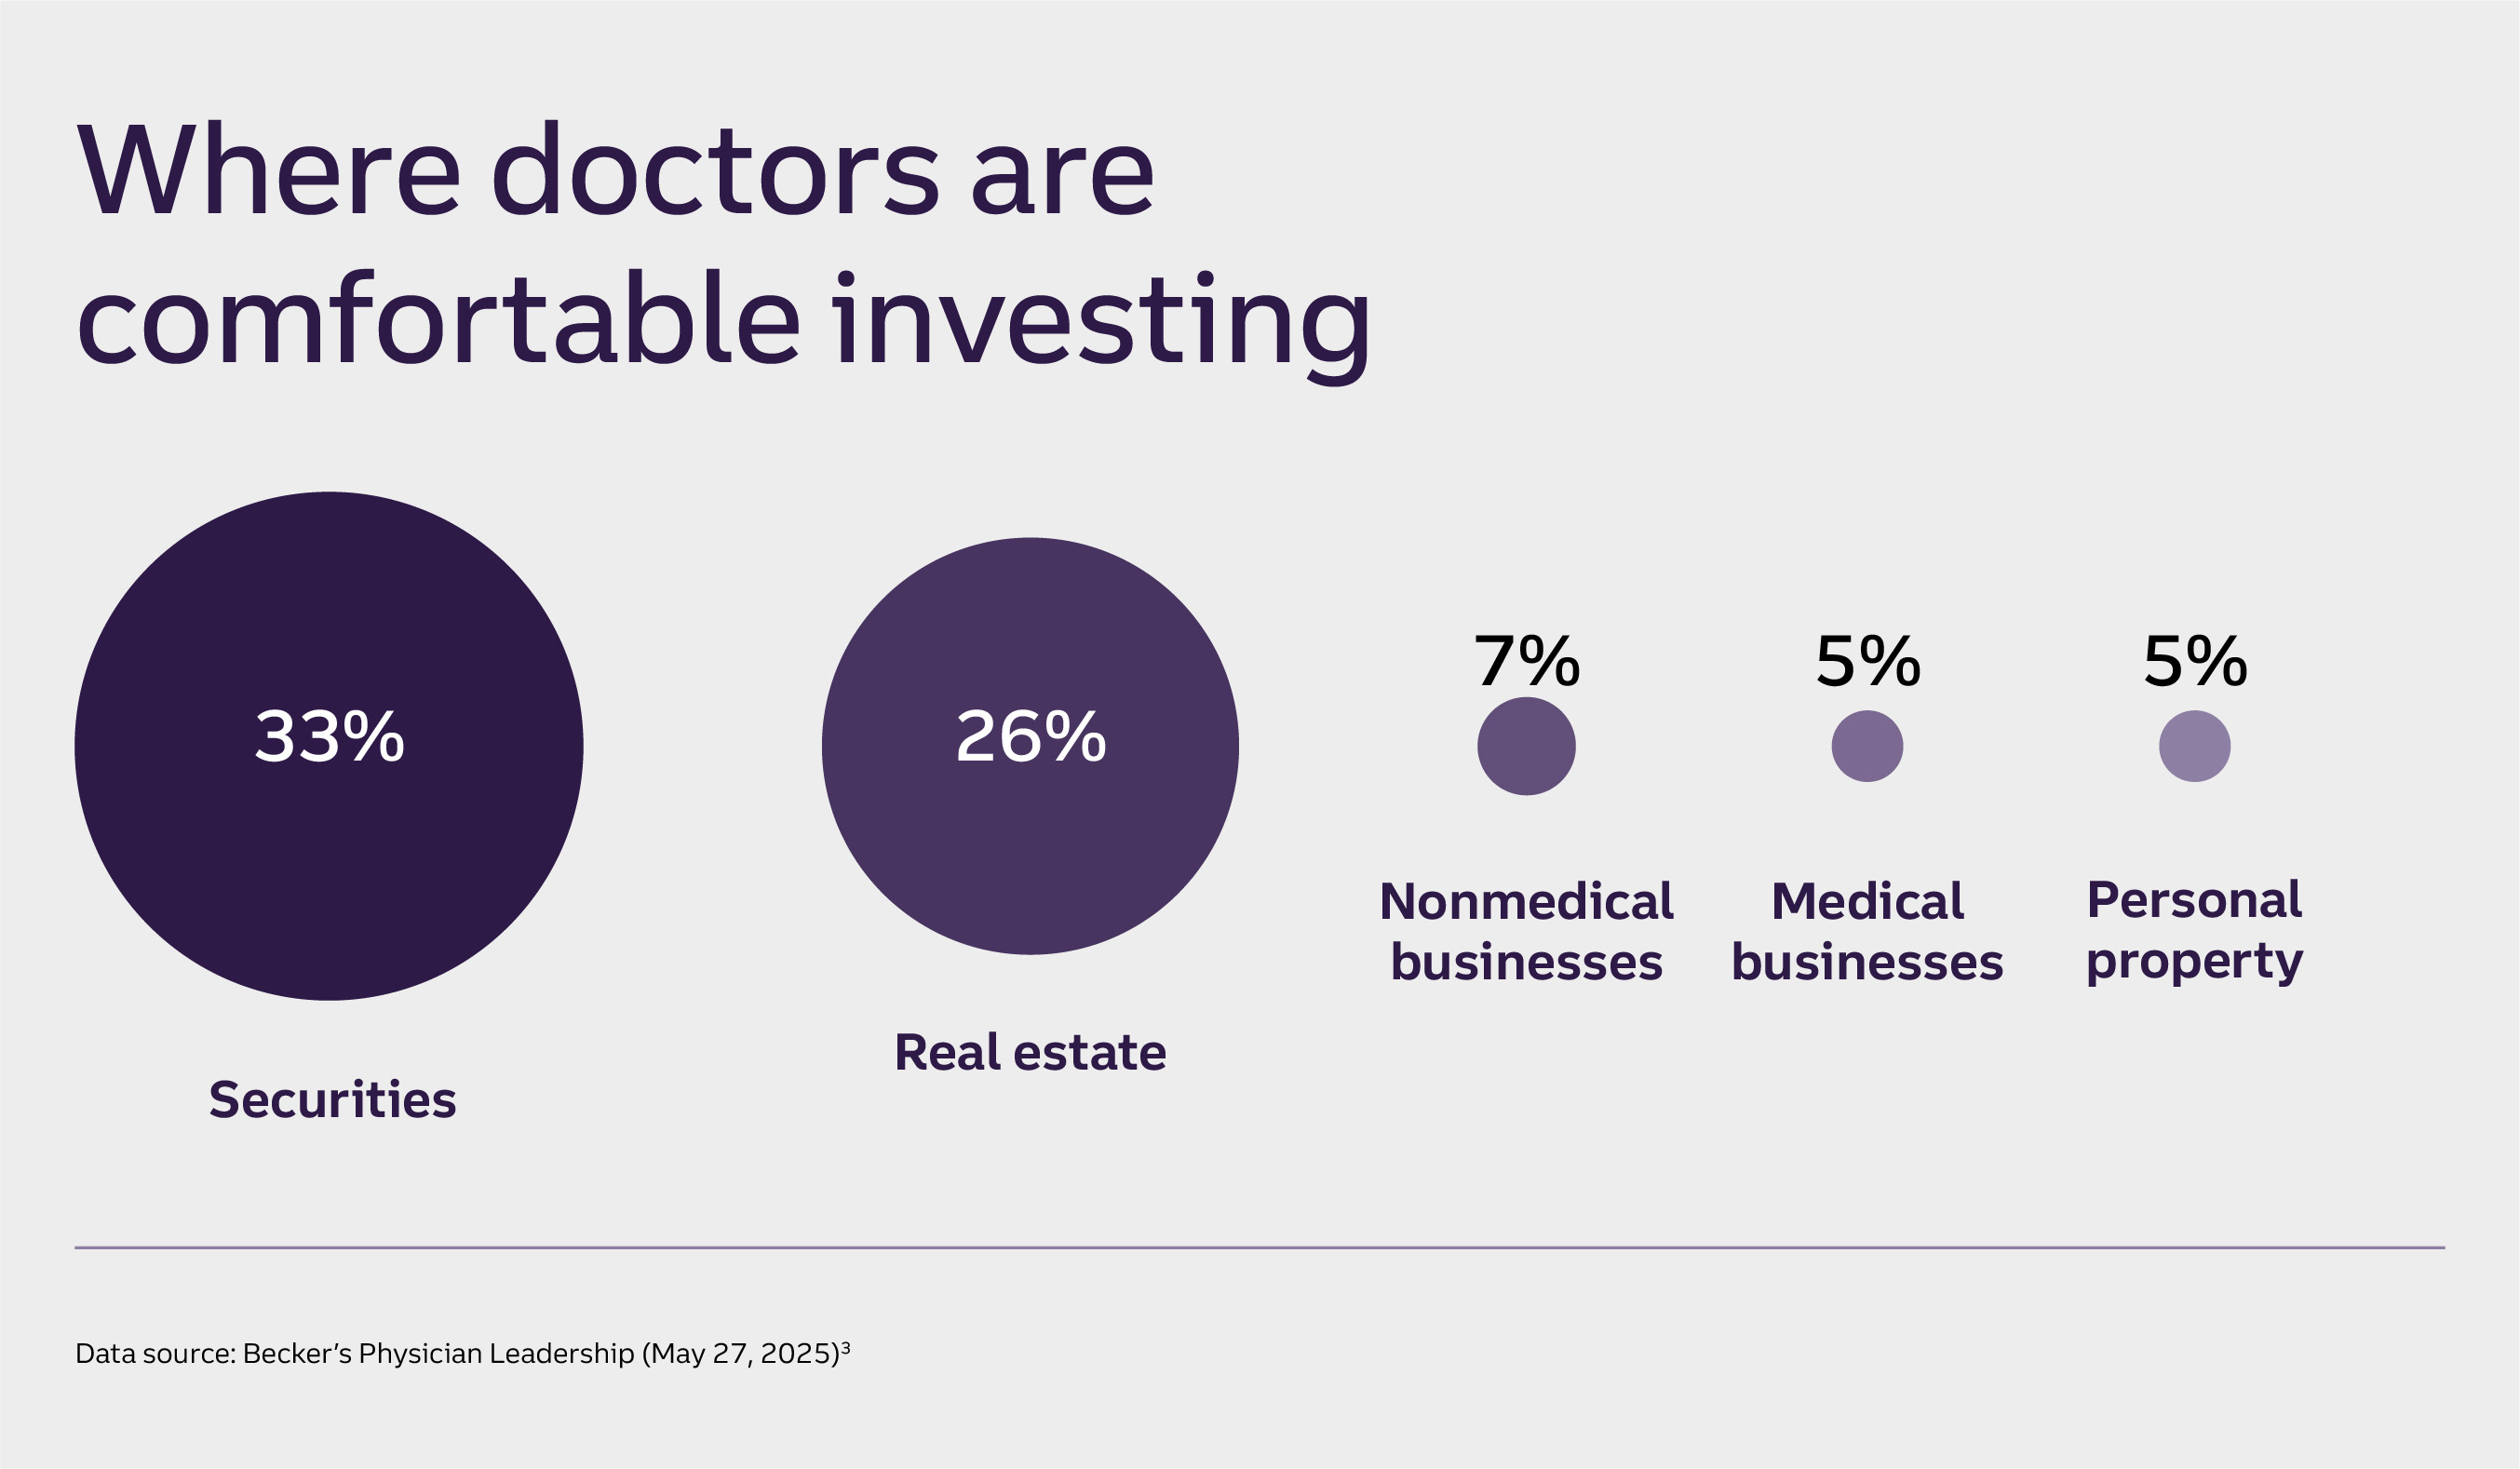
Take real estate. Just over a quarter (26%) of all surveyed physicians consider commercial real estate investment opportunities. Despite being essentially illiquid, commercial properties have dual potential to appreciate and generate income.Disclosure 3 These attributes can help you:
- Enhance cash flow
- Increase liquidity
- Diversify your portfolio
- Hedge against inflation
Because real estate investments can be depreciated over time, they also present tax and estate planning benefits. For example, given their illiquid nature, the interest you earn from properties like multifamily units can typically be placed in a trust at a discounted value—making this an excellent way to transfer wealth across generations with minimal tax burden.
We regularly work with established physicians to explore ways to extract liquidity from a variety of assets.
-Neil Horowitz, Wealth Advisor, Truist Wealth Medical Specialty Group
Keep in mind that different properties have distinct risk-return profiles that need to be factored into your investment decisions. Any potential for big returns should be counterbalanced with extensive due diligence, professional insight, and guidance that helps ensure the risk-return trade-off meets your needs and expectations, including the fact that the property could decrease in value.
4. Preserve retirement assets as your last option for pre-retirement cash.
Many medical professionals have a large portion of net worth put to work in tax-smart retirement accounts. Withdrawals from a 401(k) or IRA before age 59 1/2 generally trigger an automatic 10% IRS penalty. You’ll immediately owe personal income tax, which can greatly reduce your net cash from the withdrawal. Most significantly, both withdrawals and loans from your plan can severely impair your ability to reach your long-term goals and have financial security in retirement.
Healthcare professionals are expanding their portfolios with liquid, easily accessible assets alongside their retirement savings, and they are seeking expert advice to do it. In a 2024 survey of more than 7,000 U.S. physicians, 44% reported moderately or considerably researching investment opportunities outside retirement accounts. More than 60% reported seeking professional advice before making investment decisions.Disclosure 4
Your Truist Wealth advisor can bring in retirement, real estate, and other specialists from across the bank. As a team, they’ll listen to your goals, assess your current position, collaborate with you on a plan of action, and measure progress toward the financial outcomes that matter to you.
What challenges are you facing with your personal wealth?
Talk to your wealth advisor or reach out to Truist Wealth Medical Specialty Group to start a conversation.